Venmo
VenmoFinanceVerified
- 344.40K Reviews
- 4.1
- Downloads
- 50,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When I think about what makes Venmo stand out from a basic bank transfer, I keep coming back to its social payment feed. It puts shared expenses in a familiar, conversational setting, which can make it easier to keep up with who has paid and what a payment was for. That approach is useful when the people involved already use the app, but it also means I pay attention to privacy and payment details rather than treating every transaction as an invisible bank movement.
A payment feed that adds context
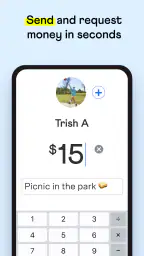
Venmo is a finance app developed by Venmo, and its central idea is simple: send and receive personal payments while attaching a note that gives the transaction some context. In everyday use, that note can help distinguish a dinner contribution from a ticket repayment. The social layer makes those exchanges feel less formal than a conventional banking app, though it is not a reason to share information casually. I would choose a clear, modest note and check who can see the transaction before sending it.
The app is free, rated for Everyone, and has an average rating of 4.1 from around 881,000 ratings. It has been installed over 50 million times, which helps explain why it may already be familiar to friends or roommates. Venmo first appeared in May 2010, and version 10.80.0 is listed for devices running Android 8.0 or later. Those details make it easy to identify the app, but the practical question is whether the people you regularly pay are willing and able to use the same service.
The Social Payment Experience
One of the first things you'll notice about Venmo is its social media-like feed. When you open the app, you might feel like you're on a social network rather than a payment app. You can see who paid whom for what (unless they set the payment to private). It's kinda fun to see quirky payment descriptions, and it adds a personal touch that makes the app more engaging than your typical banking app.
Easy Peasy Setup
Setting up Venmo is a breeze. You just download the app, link it to your bank account or credit card, and you’re good to go. The app guides you smoothly through the setup process, and in no time, you’re ready to make your first transaction. I found it super intuitive, even if you’re not tech-savvy.
For a smoother first payment, I’d take a moment to make sure I have the right recipient before confirming anything. A familiar name or profile is not a substitute for checking the details, especially when money is involved. I would also settle on a short, recognizable description with the other person. That small bit of coordination makes a later glance at the feed or payment history more useful, without turning a simple repayment into a confusing message exchange.
Splitting Bills Made Simple
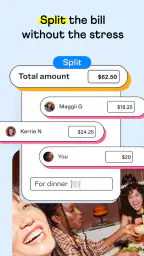
If you’ve ever struggled with splitting a dinner bill, you’ll love how Venmo handles it. You can split costs directly in the app with just a few taps. It does the math for you, which is a lifesaver if you’re not a fan of mental arithmetic. Plus, you can add a note to your payment, like "for the best tacos ever"—always a nice touch.
Other Stories to Read




The best use case I see is a group that has a clear agreement about the total and each person’s share. Imagine friends ordering food together: one person pays the restaurant, then the others send their portions with notes that identify the meal. It keeps the repayment visible to the group and avoids a string of vague messages like “what did I owe you?” But I would still check the amounts before sending. A calculation can divide a bill; it cannot know whether someone ordered separately, shared an extra item, or already covered a tip.
Security You Can Trust
Security is a big deal when it comes to handling money, and Venmo doesn’t disappoint. It offers multiple layers of protection, including PIN codes and biometric security like fingerprint recognition. Honestly, I felt pretty safe using it, knowing that my transactions were secured.
Even with those protections, I treat the social and security choices as separate questions. A PIN or fingerprint can help protect access to an account, while privacy settings shape what other people can see about payments. Before using the app regularly, I would review those settings and decide what I want visible rather than assuming a payment is private by default. That is especially sensible if I use payment notes that could reveal where I spend time or who I pay.
Instant Transfers (For a Fee)
If you’re in a rush to get your money, Venmo offers instant transfers to your bank account. It’s a nifty feature, though it comes with a small fee. Otherwise, you can opt for the standard transfer, which is free and takes a couple of days.
That choice is mainly about timing, not a reason to transfer every balance immediately. If I do not need the money in my bank account right away, the standard route is the more sensible option described here; if timing matters, I would weigh the fee against the convenience before choosing instant transfer. Venmo is less compelling for someone who wants every payment to move directly through their usual bank tools, or who dislikes having to make that speed-versus-cost decision.
The Social Scene
Venmo's social features are both a hit and a miss. While it's fun to see what your friends are up to, there are times you might want a bit more privacy. Thankfully, you can adjust your settings to make transactions private. It’s a little like being your own social media manager, deciding what to share and what to keep under wraps.
Compared with a bank transfer, Venmo makes the purpose of a casual repayment easier to recognize through its note and social context. Compared with a cash handoff, it gives friends a way to settle up without coordinating exact bills in person. But neither comparison makes it the right tool for every situation: if someone in the group does not use it, if you need a formal record for business accounting, or if you prefer payment activity to have no social dimension, a bank’s own service or another payment method may fit better. The useful distinction is not which option is universally best, but which one the people involved can use comfortably and consistently.
For a recurring shared expense, I would use the notes as lightweight bookkeeping rather than relying on memory. A household could agree to label repayments consistently—such as by month and expense—so entries are easier to recognize later. That is not a replacement for a proper budget or a shared expense ledger, but it can reduce confusion when several small repayments happen close together. The trade-off is that everyone needs to follow the same habit; inconsistent notes quickly lose their value.
People often wonder whether they need to use Venmo for every payment once they install it. I would not. It makes most sense as a convenient option for personal exchanges with people who already use it, while a bank transfer or cash can remain the better fit for other recipients or more formal arrangements. I would also decide in advance whether convenience is worth using the instant transfer option, rather than treating speed as the default. That simple choice keeps the app useful without letting a quick payment become an automatic extra cost.
Its reach is a genuine advantage, but popularity does not remove the need to check the recipient, amount, note, and visibility before confirming a transaction. Those checks are small enough to become a routine and important enough to prevent avoidable mix-ups. For readers wondering who should skip it, my answer is anyone who wants a strictly private, bank-centered experience, has no regular contacts using the service, or needs a more structured tool for tracking shared finances. They may find the social presentation unnecessary rather than helpful.
All in all, Venmo is a handy app for personal payments. It’s reliable, easy to use, and even a bit fun with its social elements. Whether you’re paying for a shared pizza or chipping in for a group gift, Venmo makes it all just a little bit easier. If you haven’t tried it yet, give it a go—you might just find it becomes a staple on your phone.
Who gets the most from it
I’d recommend it most to people who routinely split ordinary costs with friends, relatives, or roommates and want those repayments to carry enough context to be recognizable later. It is a particularly comfortable fit when the same circle uses it and agrees on privacy habits. If that describes your daily routine, Venmo can make small financial favors feel easier to settle without turning every payment into a formal chore. If not, there is no need to force it into your routine: choose the payment method your contacts can use and that matches the level of privacy and record-keeping you need.
Highlights
- Easy-to-use interface for quick payments.
- Instant notifications for transactions.
- Supports splitting bills with friends.
- Seamless integration with social features.
- Secure with multi-factor authentication.
Limitations
- Some features require a bank account link.
- Privacy concerns with transaction visibility.
- Fees for instant transfers to bank accounts.
- Limited international usage.
- Customer support can be slow to respond.
Frequently Asked Questions
01What is Venmo, and how does it work?
Venmo is a mobile payment service that allows users to transfer money to one another using a mobile phone app. Linked to your bank account, credit, or debit card, Venmo facilitates quick and easy peer-to-peer transactions. It’s often used for splitting bills, sharing rent, or reimbursing friends.
02Is Venmo safe to use for financial transactions?
Yes, Venmo employs bank-level security measures to protect users' financial information. It uses encryption to secure data and offers multifactor authentication for added protection. However, users should be cautious about sharing personal information and ensure they only transact with trusted individuals.
03Are there any fees associated with using Venmo?
Venmo is free to use for sending money from a linked bank account, debit card, or Venmo balance. However, there is a 3% fee for transactions funded by a credit card. Instant transfers to your bank account also incur a small fee, while standard transfers are free.
04Can I use Venmo for business transactions?
Venmo is primarily designed for personal transactions. However, businesses can set up a Venmo business profile to accept payments. Users should note that business transactions are subject to a fee, and Venmo’s user agreement does not cover unauthorized business use without a business profile.
05Does Venmo work internationally?
Currently, Venmo is only available for transactions within the United States. Users outside the U.S. cannot use the service, and it doesn’t support international money transfers. Those needing international payment options may need to consider other services like PayPal or Western Union.


